

Checkbook - Account Tracker
by TinyWork Apps
3.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.6
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
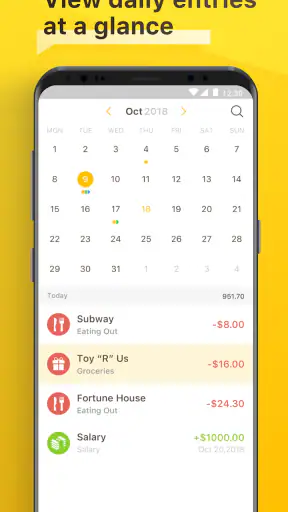
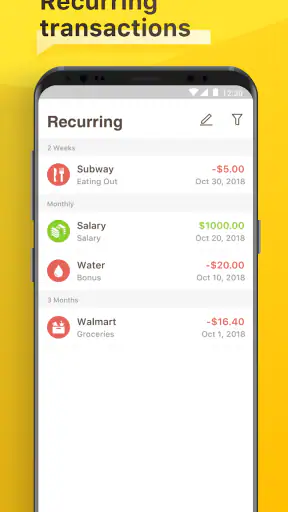
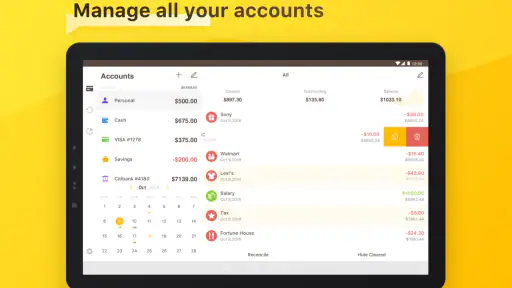
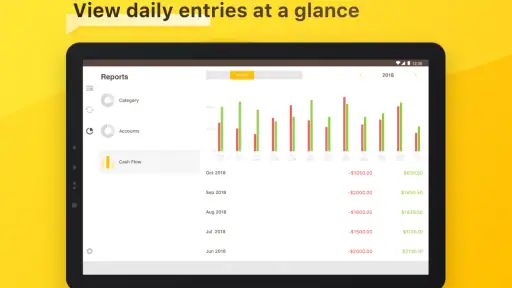
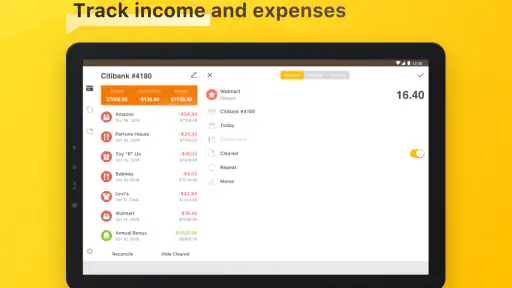
 Analysis by Getfullapps
I like the idea behind Checkbook - Account Tracker because it focuses on one job that many finance apps bury under charts, budgets, and account connections: keeping a clear running record of money going in and out. I reviewed it as a simple checkbook register from TinyWork Apps, and my impression is that it works best for people who want to enter transactions themselves and see what their balance should be after each entry.
That simplicity is both its appeal and its main limitation. This is not the kind of finance tool I would choose when I want a complete picture of several bank accounts, automatic categorization, investment tracking, or a polished household budget. I would consider it when I want a lightweight ledger that behaves more like a digital version of the paper register many people used with a checking account.
The app is free to install, has an Everyone content rating, and runs on Android versions from 7.0 onward. It has reached over 100 thousand installs, with an average rating of 3.6 from around 9 thousand ratings. Those figures suggest a useful but somewhat mixed experience: enough people rely on it for basic tracking, while the rating also hints that setup, expectations, or day-to-day handling may not suit everyone.
Where the simple register can still cause friction
The first thing I would explain to a friend is that a checkbook register depends on disciplined entry. The app can only show a useful balance when transactions are recorded consistently. If I pay with a card, forget to enter it, and then compare the app with my bank later, the problem is not necessarily a calculation error. The register is reflecting the information I gave it, not silently reconstructing my spending.
That distinction matters because many modern finance apps train users to expect automatic imports. Checkbook - Account Tracker takes the opposite approach: it is most comfortable when I remain responsible for the ledger. For someone who enjoys that control, manual entry can be reassuring. For someone who wants the app to discover purchases in the background, it can quickly feel like extra work.
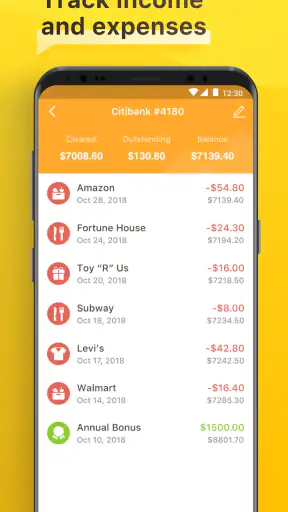
Another common sticking point is the difference between a bank balance and a register balance. A bank may show money that is available immediately, while a checkbook-style record may include transactions I have entered but that have not cleared yet. If those two numbers do not match, I would first inspect pending checks, card purchases, transfers, and recent deposits before assuming the app is wrong.
This is also why I would avoid entering a transaction twice just because it has not appeared in the bank yet. Duplicate entries are easy to create when I use the app as a personal record and then later try to “catch up” from a statement without checking which items are already present. A clean register needs a single, repeatable method of recording each movement of money.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What to decide before entering the first transaction
Before using it seriously, I would choose one purpose for the register. It could be the checking account used for everyday bills, a personal spending account, or a way to track a shared account manually. Mixing several unrelated balances into one mental workflow makes the result harder to trust, even if every individual entry is correct.
I would also decide whether to record transactions when they happen or when they clear. Either method can work, but switching between them creates confusing differences. My preference is to record a purchase when I make it, then treat the running total as an expected balance. That gives me an earlier warning that upcoming payments may leave less money available than the bank’s current figure suggests.
For people who still use checks, the register concept is especially natural. A check can be written down immediately, even before it reaches the account. For card users, the same habit works, but it requires remembering that the transaction may remain pending for a while. The important point is not which method I choose; it is that I use the same method every day.
Setup checks that prevent later confusion
I would begin with a known starting balance rather than guessing. The most useful starting point is the balance from a recent statement or the bank at the moment I begin, followed by any transactions that have not yet cleared. If I start with an approximate number, every later balance may look suspicious even when the entries are accurate.
Next, I would add only a few current transactions and compare the result with the account. This small test is more useful than entering months of history immediately. It confirms that I understand how the app treats amounts, deposits, withdrawals, and the running balance before I depend on it for a larger record.
When an amount looks wrong, I would check the sign and decimal placement first. A deposit entered as money leaving the account can make the balance appear dramatically incorrect, while a missing decimal can create an error that is easy to overlook in a long list. I would also review whether a transaction was entered twice under slightly different descriptions.
The current version is 2.1.2, and the application supports Android 7.0 and newer. That makes it suitable for many older Android phones, but compatibility is not the same as identical behavior on every device. If the screen is cramped, text is difficult to read, or input feels unreliable, I would first update the operating system and the app where possible, then restart the phone before treating the issue as a bookkeeping problem.
A safer way to build a reliable routine
I find manual finance tools work better when they are attached to an existing habit. For example, I might enter purchases after checking a receipt, or update the register once each evening before looking at the bank balance. Waiting until the end of the month creates a memory exercise, and small forgotten purchases are exactly what make a manually maintained register lose credibility.
I would keep descriptions short but meaningful. “Groceries” is more useful than a vague note such as “card,” while “rent” or “electricity” makes later checking easier. I would not try to turn every entry into a detailed budgeting record unless I had a clear reason. The strength of this app is the running account record, not the amount of information I can force into each transaction.
There is also a useful trade-off between speed and precision. If I enter every detail immediately, the register is more complete but may interrupt daily life. If I postpone everything, I save time now but increase the chance of omissions. A quick entry at the moment of payment, followed by a short review later, is the compromise I would use.
Recovering the workflow when the balance looks wrong
When a register stops matching the bank, I would not erase everything and start again. I would work backward from the last point where the two balances agreed. From there, I would compare transactions one by one, beginning with the newest entries. This approach usually reveals a missed deposit, a repeated payment, a forgotten fee, or a transaction recorded with the wrong direction.
A practical recovery routine is to separate the difference into categories. First, look for items that are in the app but have not cleared at the bank. Then look for bank activity that is missing from the app. Finally, check arithmetic details such as the amount, date, and whether the entry was treated as money in or money out. This is faster than randomly editing old transactions.
If I use the app for a shared account, I would agree with the other person on who records what. Two people entering the same purchase is just as damaging as neither person entering it. A simple rule, such as one person recording card spending and the other confirming deposits, can prevent duplicate work without requiring a complicated system.
I would also be cautious with transfers between accounts. A transfer is not new income for the household, even though one account increases and another decreases. If I maintain separate records, the same movement needs to be represented consistently on both sides. If I only track one account, I would record the effect on that account and avoid counting the money as earnings.
When the app is not the cause
Some apparent problems come from the surrounding account rather than the software. A bank can authorize a card payment, place a temporary hold, reverse a charge, or post a deposit later than expected. A manually maintained register will not automatically know why the bank’s available balance changed. In that situation, the bank’s transaction history and statement are the right places to investigate.
Likewise, a mismatch may come from comparing different definitions of “balance.” The bank’s available amount can differ from the ledger total because of pending activity. I would write down both figures and label them clearly instead of trying to make one number explain the other. The register is valuable precisely because it can show what I have committed to spend, not only what has already settled.
If the app closes, stops accepting input, or behaves strangely, I would use ordinary troubleshooting first: close and reopen it, restart the device, check for an available update, and confirm that the phone still has enough free space for normal operation. I would avoid repeatedly changing entries while the app is unstable, because that can make it harder to know which transactions were actually saved.
For important financial records, I would keep a separate reference during a cleanup. A recent bank statement or a handwritten list of the last confirmed entries gives me something to compare against. That is not a criticism unique to this app; any manual finance ledger deserves a backup habit because a single device should not be the only place I remember my account history.
Who gets the most value from this approach
I think this app is a good fit for someone who wants a focused checking-account register and is comfortable entering transactions personally. It may suit a student learning to manage a first account, a person who prefers not to connect financial accounts to another service, or someone replacing an old paper checkbook with a phone-based record.
It can also help someone who needs a “committed spending” view rather than a broad financial dashboard. If I have several bills scheduled and want to know how the balance may look after they are entered, a register gives me a direct answer. That is different from opening a banking app and seeing only the amount currently available.
I would skip it if my main goal is automatic bank synchronization, detailed category reports, shared real-time budgeting, or a complete view of savings, credit cards, and investments. A dedicated budgeting platform or the bank’s own application may be better for those jobs. I would also avoid relying on it as my only tool if I rarely remember to enter purchases; the manual workflow is a feature only when I can maintain it.
How it compares with paper and larger finance apps
Compared with a paper register, the phone-based version is easier to keep nearby and less vulnerable to smudged writing or a lost pen. It is also more convenient for checking the running figure before making a purchase. The trade-off is that paper can feel more transparent: I can see every handwritten correction, while a digital list may require more attention when tracing how a balance changed.
Compared with a bank app, this tool gives me more control over what I consider pending or committed. The bank remains better for confirmed transactions, security notices, and the official account balance. I would use the two together rather than treating one as a replacement for the other: the bank tells me what has posted, while the register helps me plan around transactions I already know are coming.
Compared with full budgeting software, the lighter scope is refreshing. There are fewer reasons to spend time configuring categories and financial goals if all I need is a register. But that same narrow focus means I should not expect the kind of summaries, automation, or cross-account analysis that makes larger finance tools worthwhile. Choosing this app is mainly a choice to keep the system small.
Cost, expectations, and everyday use
The app is free, with optional in-app purchases ranging from under a dollar to around twenty dollars per item. I would start with the free experience and decide whether it covers my register needs before paying for anything. Since the basic appeal is simplicity, I would judge an upgrade by whether it removes a real obstacle in my routine, not by adding options I will never use.
For an everyday scenario, imagine I receive a paycheck, pay rent, use a debit card for groceries, and have a utility payment scheduled. I would enter the deposit, record rent and groceries as they happen, and add the upcoming utility payment so the running figure reflects the money already spoken for. Before buying something optional, I would check that adjusted balance rather than relying only on the bank’s current available amount.
At the end of the week, I would compare the register with the bank and mark the point where cleared activity matches. If there is a difference, I would investigate while only a handful of transactions are involved. This weekly check is the practical habit that makes the app useful; without it, a missed entry can remain hidden until the numbers become difficult to untangle.
My overall view is that Checkbook - Account Tracker is best understood as a focused manual ledger, not a modern all-in-one financial manager. TinyWork Apps has kept the concept approachable, and that can be exactly what a person wants when paper feels outdated but a large budgeting platform feels excessive. The 3.6 average rating also encourages realistic expectations: the app is not universally effortless, particularly for users who expect automation.
My practical verdict: I would recommend it to a careful user who wants a straightforward account register and is willing to maintain it regularly. I would not recommend it to someone looking for automatic updates or broad financial analysis. Start with a verified opening balance, enter a small test set, compare it with the bank, and adopt one consistent recording habit. If that routine feels natural, this free finance app can be a useful replacement for a paper checkbook; if manual entry already sounds like a chore, a connected banking or budgeting alternative will probably serve you better.
Pros
- Simple interface makes recording income and expenses quick.
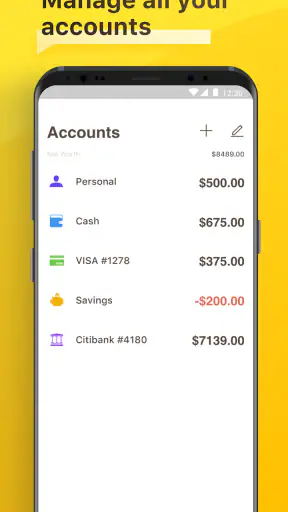
- Supports multiple accounts for better financial organization.
- Useful balance history helps track changes over time.
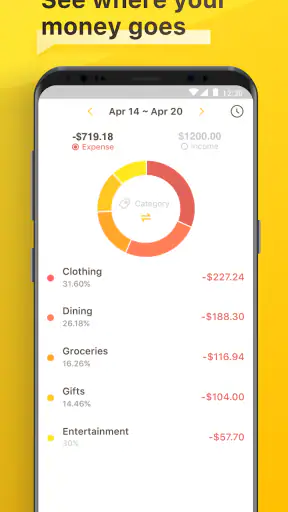
- Custom categories make transactions easier to sort and review.
- Can help users monitor spending without linking a bank account.
Cons
- Manual entry can become tedious for frequent transactions.
- Some advanced features may require an in-app purchase.
- Limited automation compared with full-featured budgeting apps.
- No bank synchronization may mean balances need regular updates.
- Users may need time to configure categories and account settings.
FAQs for Checkbook - Account Tracker
What is Checkbook - Account Tracker used for?
Checkbook - Account Tracker is designed to help you manage personal finances by recording income, expenses, deposits, withdrawals, and transfers in one place. After entering your transactions, you can review your current balance and monitor how money moves between accounts. It is especially useful for people who want a simple alternative to paper checkbooks or complex budgeting platforms.
Can I use Checkbook - Account Tracker to manage multiple accounts?
Yes, the app is suitable for tracking more than one financial account, such as checking accounts, savings accounts, cash, credit cards, or other personal funds. Keeping accounts separate makes it easier to understand where your money is held and prevents transactions from being mixed together. Before downloading, check the current store description because account limits and some advanced options may depend on the version.
Does Checkbook - Account Tracker connect directly to my bank?
The app is primarily intended for manual transaction tracking rather than replacing your bank’s official application. You generally enter transactions yourself, which gives you control over the information recorded but requires consistent updates. This approach can be helpful for privacy-conscious users, although anyone expecting automatic bank synchronization, live balances, or automatic transaction imports should confirm whether those features are available in the latest release.
Is my financial information safe when using the app?
Because Checkbook - Account Tracker may contain sensitive details about your spending and account balances, you should review its privacy policy and security settings before relying on it. Avoid entering unnecessary banking credentials or full card information, and use any available passcode, biometric lock, backup, or export protections. The app should be treated as a personal record-keeping tool, not as a replacement for secure banking services.
Is Checkbook - Account Tracker suitable for budgeting and expense analysis?
The app can be useful for basic budgeting because recording transactions helps you see spending patterns and maintain more accurate account balances. However, its main strength is checkbook-style tracking, so it may not provide the same depth as dedicated budgeting applications with extensive categories, financial goals, charts, recurring bill tools, or bank synchronization. It is a good choice for straightforward monitoring, provided you enter transactions regularly.

Checkbook - Account Tracker
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via checkbook@support.polycents.com, visit https://www.polycents.com, or review their https://apps.polycents.com/Checkbook/PrivacyPolicy.










